September 17, 2026
The Federal Reserve Removes a Dose of Accommodation
KEY SUMMARY POINTS
- The U.S. Federal Reserve (Fed) raised the fed funds rate by 25 basis points (bps), bringing the target range to 3.75% - 4.00%.
- Updated projections showed slightly stronger economic growth and higher inflation than previously expected.
- The median interest rate projection suggests one additional 25 bps increase before year-end, followed by no changes to monetary policy in 2027.
A TIMELIER RETURN TO TARGET
The Federal Reserve raised the fed funds rate by 25 bps, bringing the target range to 3.75%-4.00%. The statement accompanying the decision noted that today's policy action would support a timelier return to the Committee's 2% inflation objective.
While we view underlying inflation as having eased in recent months, and remaining pressure linked to supply-side developments, Chair Warsh reiterated that summer inflation trends were not sufficient to demonstrate that price pressures are returning to target clearly and at a satisfactory pace.
The decision was also supported by a resilient economic backdrop. Throughout the press conference, Warsh highlighted solid domestic demand, robust business investment, and healthy labour market conditions, suggesting the economy remains in a position to absorb higher interest rates as the Fed maintains its focus on price stability.
US CPI Inflation
YoY % chg
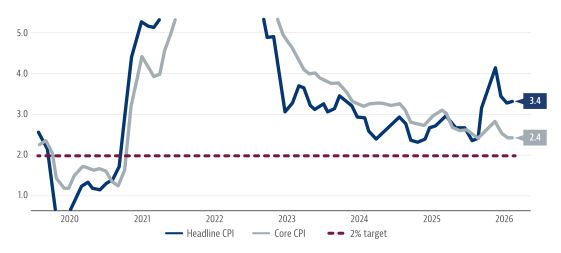
Source: U.S. Bureau of Labor Statistics (BLS), Macrobond As of September 11, 2026
A HIGHER NEUTRAL RATE COMES INTO VIEW
The updated Summary of Economic Projections showed slightly stronger economic growth and somewhat firmer inflation.
Growth was revised higher, with the median 2026 projection revised up to 2.3% (prev. 2.2%). The unemployment rate is steady at 4.1% across the projection horizon.
The median projection for core inflation was also marked up for 2026 coming in at 3.4% (prev. 3.3%) and remaining above target through end-2028. Notably, the neutral rate was revised slightly higher on the back of these developments.
Longer Run Fed Funds Rate Projection (Neutral Rate Estimate)
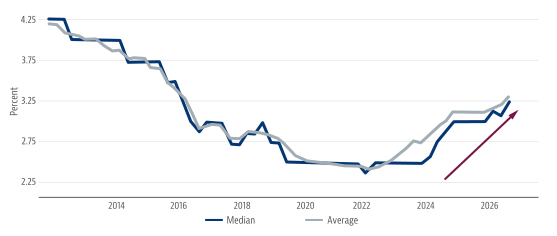
Source: Federal Reserve, Macrobond As of September 16, 2026
WHAT’S NEXT?
Chair Warsh offered few clues about the future path of interest rates, instead emphasizing the Fed's commitment to restoring price stability.
The median dot points to one additional 25 bps hike before year-end and no change in policy throughout 2027. However, the 2027 median masks a closely divided Committee, suggesting some policymakers still see scope for another 25 bps hike should inflation fail to show sufficient progress toward the Fed’s 2% target.
Beyond that, policymakers appear comfortable sitting on the sidelines unless inflation progress stalls.
To open this article in a shareable format, click here.
GLOSSARY OF TERMS
PCE: Personal Consumption Expenditures
About the Author
Neil Shankar is CI Global Asset Management’s Economist, responsible for monitoring key macroeconomic trends and shaping CI GAM’s economic outlook. He actively participates in investment and asset allocation discussions, helping guide decision-making.
A leading contributor to CI GAM’s Capital Insights publication, Neil shares in-depth perspectives on evolving economic conditions. He also frequently engages with stakeholders throughout the organization and externally, helping to deepen understanding of the economic landscape. He is regularly quoted in the press for his views on the economy and markets.
With over 10 years of industry experience, Neil joined CI GAM in 2024 after holding similar roles at other major Canadian financial institutions. Neil holds an MA in Business Economics from Wilfrid Laurier University and a BA (Honours) in Economics from The University of Western Ontario.
IMPORTANT DISCLAIMERS
This document is provided as a general source of information and should not be considered personal, legal, accounting, tax or investment advice, or construed as an endorsement or recommendation of any entity or security discussed. Every effort has been made to ensure that the material contained in this document is accurate at the time of publication. Market conditions may change which may impact the information contained in this document. All charts and illustrations in this document are for illustrative purposes only. They are not intended to predict or project investment results. Individuals should seek the advice of professionals, as appropriate, regarding any particular investment. Investors should consult their professional advisors prior to implementing any changes to their investment strategies. The opinions expressed in the communication are solely those of the author(s) and are not to be used or construed as investment advice or as an endorsement or recommendation of any entity or security discussed.
Certain names, words, titles, phrases, logos, icons, graphics, or designs in this document may constitute trade names, registered or unregistered trademarks or service marks of CI Investments Inc., its subsidiaries, or affiliates, used with permission. All other marks are the property of their respective owners and are used with permission.
Certain statements contained in this communication are based in whole or in part on information provided by third parties and CI Global Asset Management has taken reasonable steps to ensure their accuracy. Market conditions may change which may impact the information contained in this document.
Certain statements in this document are forward-looking. Forward-looking statements (“FLS”) are statements that are predictive in nature, depend upon or refer to future events or conditions, or that include words such as “may,” “will,” “should,” “could,” “expect,” “anticipate,” “intend,” “plan,” “believe” or “estimate” or other similar expressions. Statements that look forward in time or include anything other than historical information are subject to risks and uncertainties, and actual results, actions or events could differ materially from those set forth in the FLS. FLS are not guarantees of future performance and are by their nature based on numerous assumptions. Although the FLS contained herein are based upon what CI Global Asset Management and the portfolio manager believe to be reasonable assumptions, neither CI Global Asset Management nor the portfolio manager can assure that actual results will be consistent with these FLS. The reader is cautioned to consider the FLS carefully and not to place undue reliance on FLS. Unless required by applicable law, it is not undertaken, and specifically disclaimed that there is any intention or obligation to update or revise FLS, whether as a result of new information, future events or otherwise.
CI Global Asset Management is a registered business name of CI Investments Inc.
© CI Investments Inc. 2026. All rights reserved.
